
Tokenized Sukuk on Ethereum Sepolia
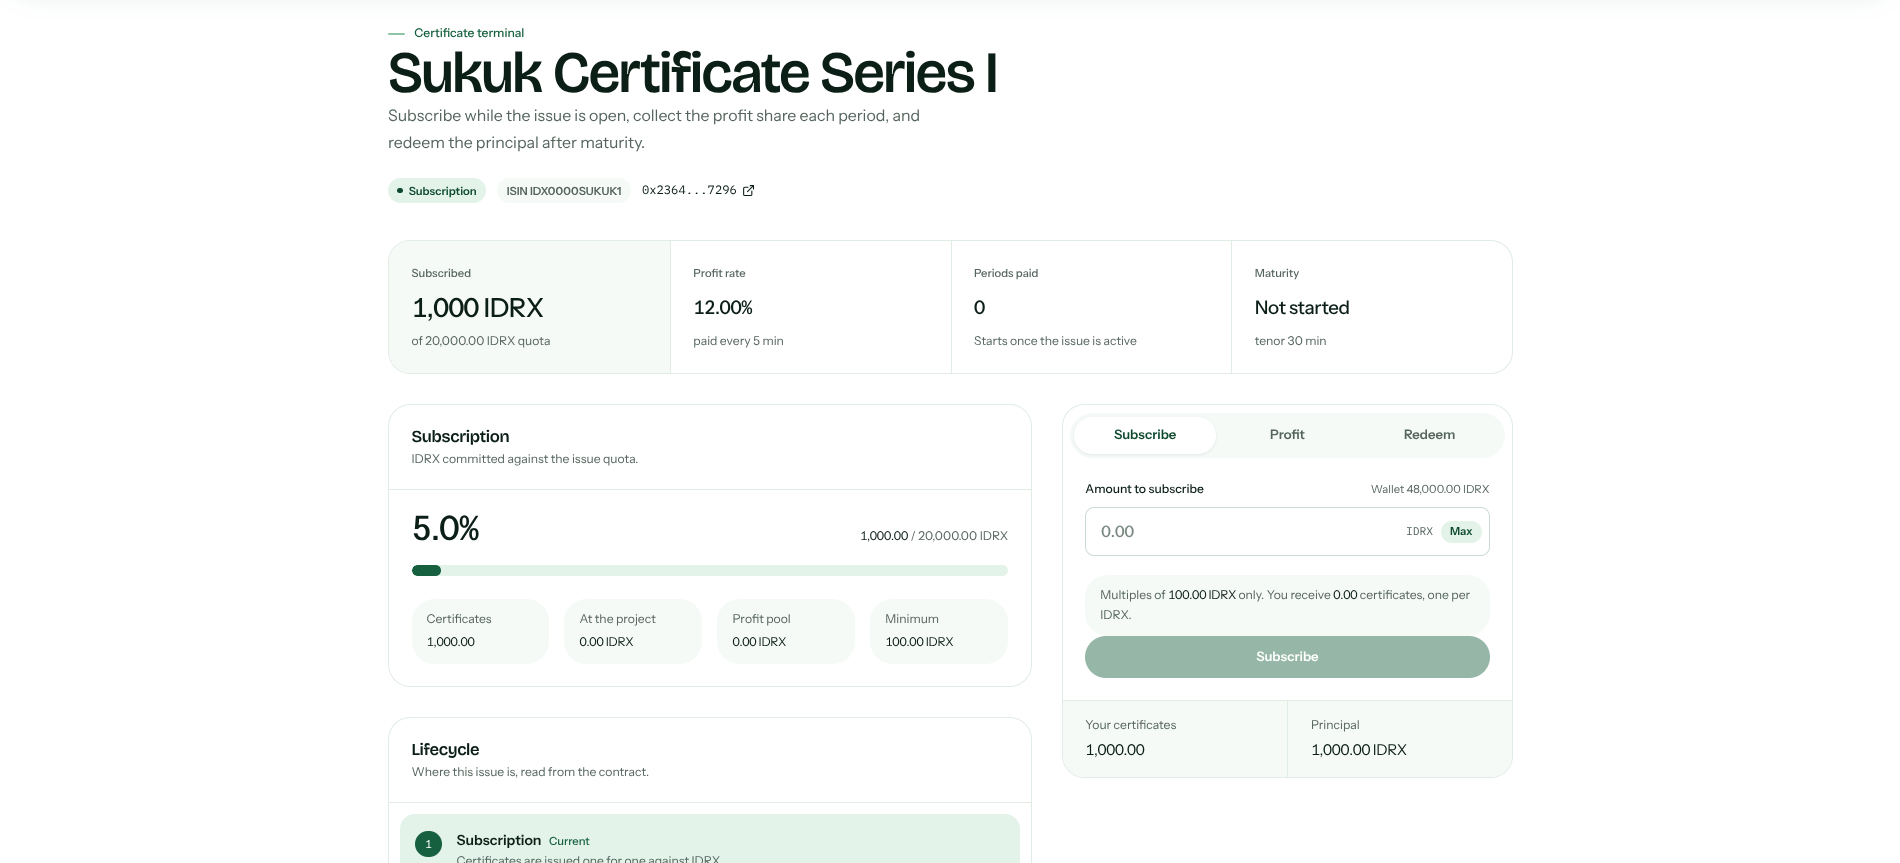
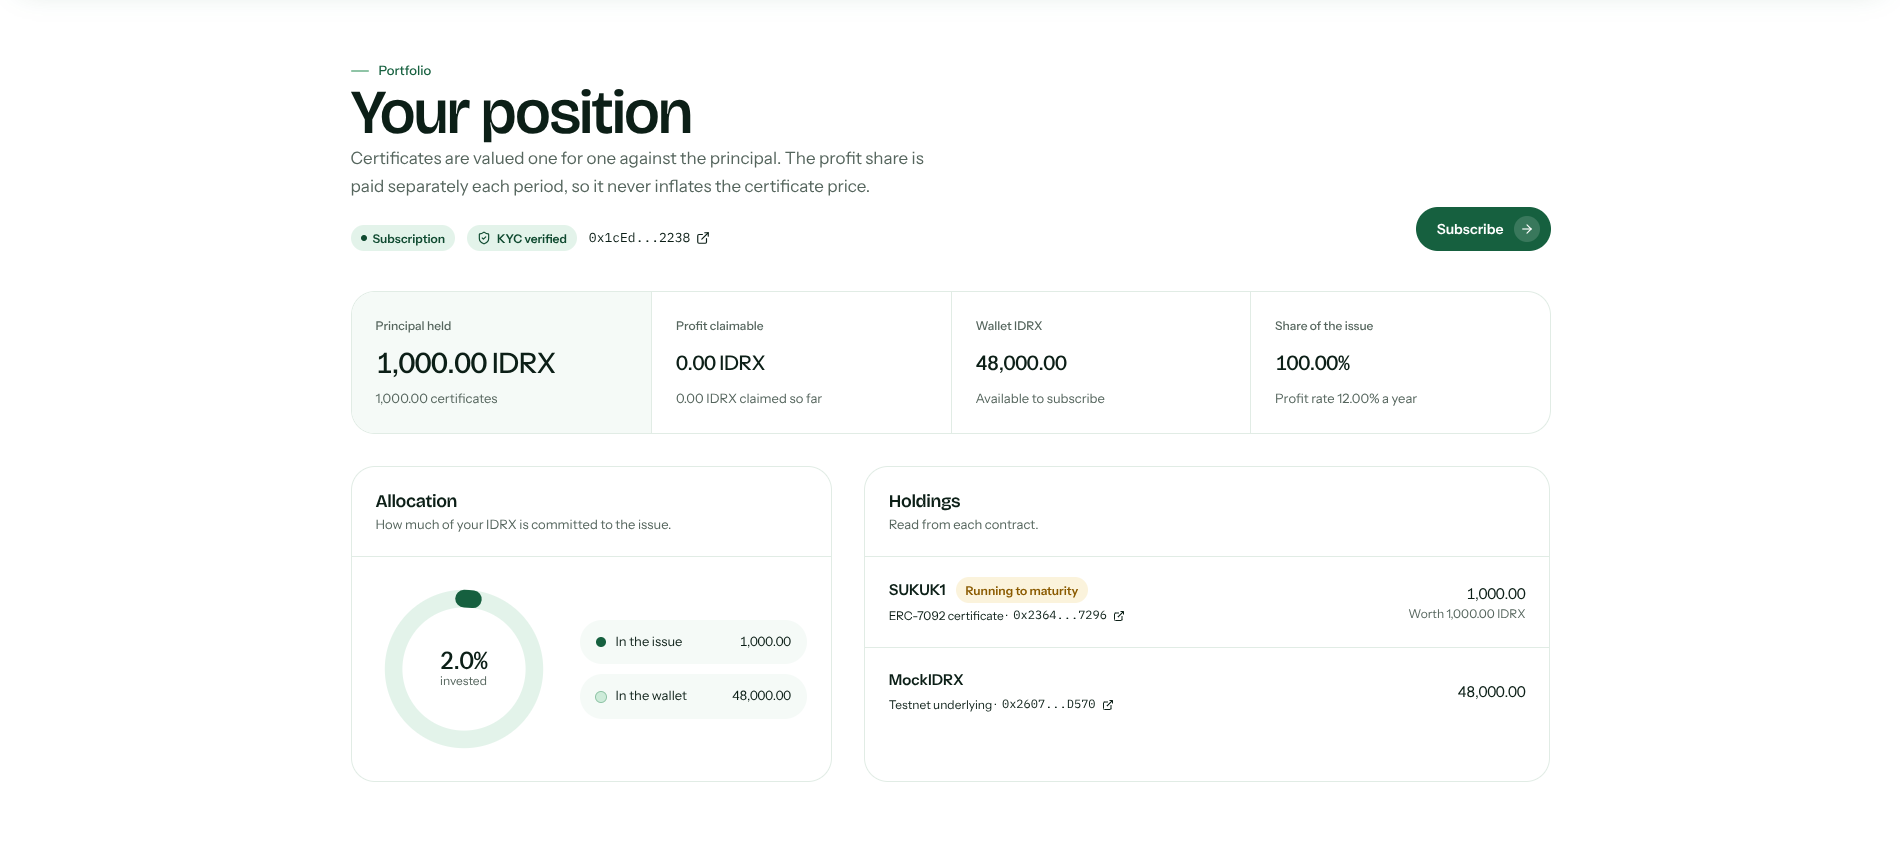
A Sukuk is an Islamic bond: investors co-own a real project and share its profit instead of earning interest. This project runs the whole Sukuk lifecycle on Ethereum, from KYC and subscription through profit sharing to redemption, settled in a Rupiah stablecoin (IDRX) and overseen by an auditor multisig. Every rupiah can be traced on-chain.
Sukuk is one of the core instruments of Islamic finance. Governments and companies use it to fund roads, schools, and green projects, and Indonesia regularly offers retail Sukuk to its citizens. But the way Sukuk is issued and held today has real gaps:
Pain point | What it means for people |
|---|---|
Opaque use of funds | Investors are told their money funds a project, but can't verify where the principal sits or whether reported profit matches the stated rate. |
Many intermediaries | Issuers, distribution partners, custodians, and registrars each keep their own records. Settlement is slow, and every layer adds cost. |
Rigid access | Fixed subscription windows, minimum ticket sizes, and paperwork keep younger and underbanked investors out. |
Manual compliance | KYC and transfer restrictions are enforced by back offices, not by the instrument itself. |
Shariah trust gap | Compliance depends on trusting off-chain reports. There is no shared, tamper-proof record that profit, not interest, was paid. |
Sukuk turns the certificate itself into the source of truth. The rules of the issue live in a smart contract that anyone can read, and no single party can bend them.
Problem | How Sukuk solves it |
|---|---|
Opaque use of funds | Principal moves only through on-chain calls into a Gnosis Safe treasury. Balances, allocations, and returns are public. |
Many intermediaries | One contract is the registry, the custodian ledger, and the payment rail. Subscription mints the certificate instantly, and profit is claimable the moment it is funded. |
Rigid access | Connect a wallet, complete KYC in one transaction, and subscribe in IDRX, a Rupiah stablecoin, in multiples of the denomination. |
Manual compliance | ERC-3643 transfer rules: the token refuses to move to any wallet that is not verified. |
Shariah trust gap | Profit sits in a separate pool, is never compounded into the principal, and the expected payout per period is published on-chain for the auditor multisig to reconcile. |
Connect wallet ─▶ Self-KYC ─▶ Subscribe (IDRX) ─▶ Hold certificate ─▶ Claim profit each period ─▶ Redeem at maturity
Verify. The investor connects a wallet and registers in the on-chain KYC registry.
Subscribe. The investor deposits IDRX and receives certificates 1:1, each one representing one unit of principal.
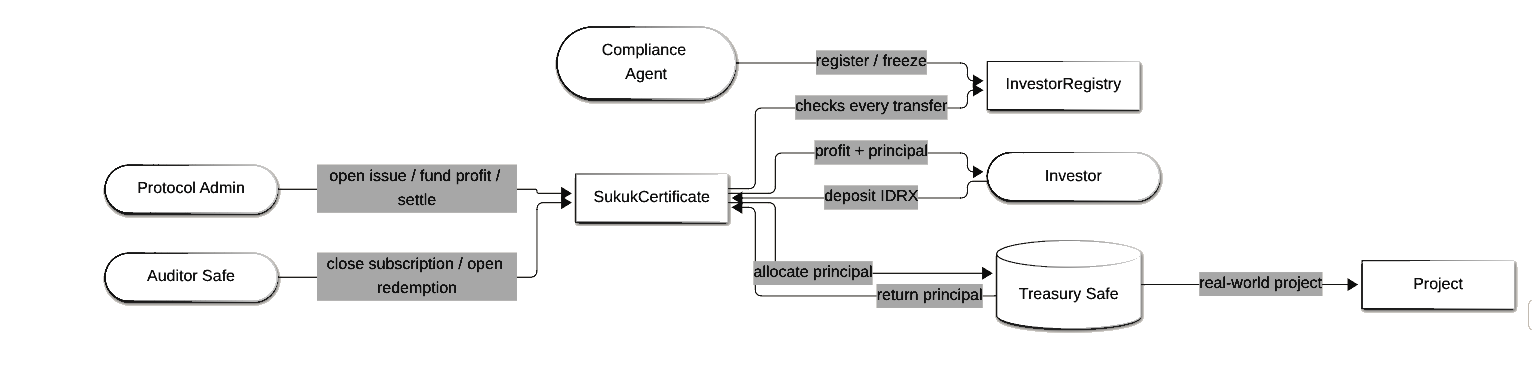
Fund the project. Once the auditor Safe closes the subscription, the principal moves to the treasury Safe that finances the real-world project.
Share profit. Every period the issuer funds the profit pool, and each holder claims their own share.
Redeem. At maturity the principal returns, the auditor Safe opens redemption, and investors request, receive settlement, and claim their IDRX back.
Every step is a public transaction, and every gate is enforced by role. The two critical transitions belong to an independent multisig, not the issuer.
Compliant by construction: only KYC-registered wallets can hold or receive the certificate. Investors complete KYC themselves right after connecting a wallet; the agent role can still remove, freeze, force-transfer, and recover wallets.
Real bond semantics: ISIN, denomination, issue volume, profit rate, issue and maturity dates are all readable on-chain.
Donation-proof accounting: principal is tracked internally, so sending tokens directly to the contract cannot move the price.
Pull-based profit: profit sits in a separate coupon pool and is claimed per holder. A transfer never carries someone else's unclaimed profit.
Two-key governance: the issuer cannot close the subscription or open redemption alone. Those gates belong to an auditor Safe that administers its own role.
Role-based dashboard: separate views for investors, the issuer, the auditor, and the compliance desk.
Standard | Role in Sukuk |
|---|---|
ERC-7092 | The certificate is the bond: ISIN, denomination, profit rate, maturity, |
ERC-4626 | Accounting. 1 certificate = 1 unit of principal, held at 1:1 for the life of the issue. |
ERC-7540 | Asynchronous redemption: request → issuer settles → holder claims. |
ERC-3643 | Transfer rules and identity registry (reduced T-REX), with freeze and recovery. |
Gnosis Safe | Auditor multisig gates the lifecycle; treasury Safe custodies deployed principal. |
Retail investors who want Shariah-compliant yield with a small ticket and full visibility.
Issuers (governments, BUMN, corporates, Islamic banks) that want faster, cheaper issuance with built-in compliance.
Auditors and Shariah boards who need a tamper-proof record instead of periodic reports.
Regulators who can watch the registry, the treasury, and every payout in real time.